Frequently asked questions
Here are the answers to some frequently asked questions. Can't find what you're looking for? Get in touch with us.
Motor
In the event of an accident, you should fill in a DAAA (Declaração Amigável de Acidente Automóvel – European Accident Statement), even if the insured vehicle went off the road and did not collide with another vehicle, person or object (for example, a motorway barrier). This is because, despite its name, the document works as a form that objectively summarises the information insurers consider necessary to correctly settle car claims.
If there is disagreement about liability for the accident, or if there are any injuries, you should always request the intervention of the police.
Then contact our team as soon as possible: we take care of all the follow-up with the insurer, so you don't have to worry about the process.
Usually you need the single vehicle document (DUA), the tax identification card of the policyholder and, if applicable, the previous insurance policy for claims history and no-claims bonus purposes.
Our team tells you, case by case, whether additional documentation is required depending on the cover you want.
The answer is no. In addition to Civil Liability cover, which is legally required and regulated, the Insured may, at their request, take out other covers known as “Own Damage” (Danos Próprios), such as Impact, Collision and Overturning, Theft or Robbery, and other types of damage that the insured vehicle itself may suffer. These special covers are commonly, though incorrectly, referred to as “all risks”.
Our team compares the options available on the market and explains, case by case, what each one covers and excludes.
As a general rule, yes, provided the driver is legally entitled to drive. Some policies apply specific conditions to young drivers or those with little driving experience, which may result in a higher excess.
If the vehicle is regularly driven by more than one person, it is worth reviewing the policy with us to avoid surprises in the event of a claim.
If the foreign-registered vehicle was insured in Portugal, you should contact the respective insurer.
If the foreign-registered vehicle was insured in another country, you should contact the Portuguese Green Card Bureau, which, as the managing bureau, will provide the name and address of the insurer operating in Portugal that will act as correspondent for the foreign insurer.
If the foreign insurer has no representative in Portugal, the bureau itself will handle the claim.
In this case, you must turn to the Car Guarantee Fund (Fundo de Garantia Automóvel – FGA), which will be responsible for paying compensation to any injured party.
The Direct Indemnity to the Insured Convention (Convenção de Indemnização Direta ao Segurado – IDS) is an agreement between insurers (signed by most insurers in the portuguese market) that aims to speed up the settlement of car claims by allowing each insured party to deal directly with their own insurer.
For a car claim to be settled under the IDS Convention, the following conditions must be met:
Direct collision between two Portuguese-registered vehicles;
Existence of valid insurance;
The losses must be material only (there can be no bodily injury);
The vehicles must be insured with two different insurers, both of which have joined the Convention;
The Car Accident Statement must be filled in (front side) and signed by both drivers, so that there is no doubt about the circumstances of the accident and the parties involved;
The accident must have occurred in mainland Portugal, the Azores or Madeira;
The claim must fall within the cases set out in the Practical Liability Table;
The cost of repairing the damaged vehicle must not exceed €15,000.00.
Under the Uniform Policy for Compulsory Car Civil Liability Insurance, issued by the Portuguese Insurance and Pension Funds Supervisory Authority (ASF), the fact that the driver responsible for the accident was driving under the influence of alcohol does not exempt the insurer from paying compensation; the insurer also remains responsible for arranging the vehicle inspection/assessment and for paying for the repair.
The Insurance Information, Mediation and Arbitration Centre (Centro de Informação, Mediação e Arbitragem de Seguros) is an entity supported and authorised by the Ministry of Justice, whose purpose is to provide information and offer alternative dispute resolution channels.
A complaint may be filed against an insurer, intermediary or insurance broker regarding a dispute arising from the formation, performance or termination of an insurance contract, regardless of the line of business.
If the parties choose to take the case to arbitration, a fee of 3% of the amount in dispute will be charged, with a minimum of €70 and a maximum of €700.
If an agreement is reached at the Mediation Conference (held prior to the arbitration hearing), each party will be reimbursed an amount equal to 25% of the amount paid.
Under the Uniform Policy for Compulsory Car Civil Liability Insurance, issued by the Insurance and Pension Funds Supervisory Authority (ASF), the premium loading applies as a result of claim(s) that have given rise to compensation payments or the setting up of a reserve, with the latter case requiring that the insurer has also accepted liability towards third parties.
In other words, in situations where, for example, the insured vehicle is hit by an unknown vehicle whose accident no one saw, and the insurer pays for the repair of the insured vehicle, there will be a loading on the policy premium.
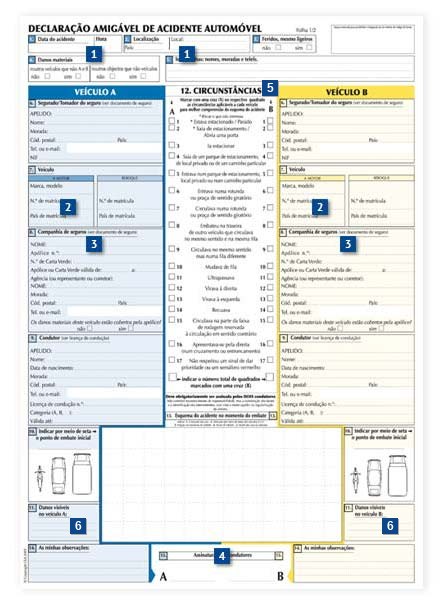
In the event of a car accident, we recommend filling in the Car Accident Statement (DAAA) together with the other party involved.
At the scene of the accident, it is essential to fill in (on the front of the Statement):
1 - Date and place of the accident
2 - Registration plates of the vehicles involved
3 - Insurance policies and insurers of the vehicles involved
4 - Whenever possible, the signatures of the drivers
5 - Circumstances of the accident
6 - Damage to the vehicles
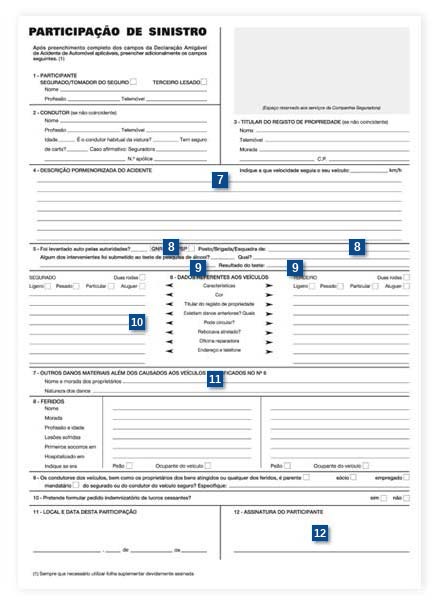
It is also important that the following information be filled in by our Client/Driver (on the back of the Statement):
7 - Detailed description of the accident
8 - Involvement of the authorities and their identification
9 - Breathalyser test and the result obtained
10 - Whether the vehicle was immobilised as a result of the accident
11 - Other damage, in addition to the vehicles involved
12 - Finally, the signature of the Policyholder or company stamp (if a company)
Health Insurance
Depending on the plan chosen, health insurance covers medical consultations, diagnostic tests, treatments, surgery and hospitalisation within a network of contracted providers, with full or partial reimbursement of costs.
Our team helps compare plans from different insurers to find the cover best suited to your profile and budget.
Yes. Most plans apply waiting periods, shorter for consultations and tests and longer for hospitalisation, surgery and childbirth. During that period the cover cannot yet be used.
Before you take out cover, we explain exactly which waiting periods apply to each benefit in the plan under consideration.
Conditions that already exist at the time cover is taken out are, as a rule, excluded. Some insurers allow them to be included subject to an individual clinical assessment and specific conditions.
Our team helps prepare the initial health declaration, which is the document where this question is decided.
In most plans, yes, through the reimbursement scheme: you pay for the consultation or test and then receive the reimbursement set out in the policy, usually lower than within the contracted network.
We compare with you the balance between network and reimbursement cover in each plan, because that is where plans differ most.
Insured Person(s)
Individual Medical Questionnaire (if applicable)
Clinical documentation, if requested by the insurer for the purposes of risk acceptance
Health insurance typically does not cover:
Occupational diseases and workplace accidents;
Nervous disorders and psychiatric conditions;
Disorders caused by alcohol or drug abuse;
Accidents or illnesses resulting from participation in sports competitions;
Weight-loss treatment or surgery;
Fertilisation or any artificial insemination method;
Organ or bone marrow transplants;
Cosmetic, plastic or reconstructive treatment or surgery and its consequences (unless required as a result of an illness or accident covered by the insurance);
Stays in psychiatric institutions, spa/thermal establishments, rest homes, care homes for the elderly, or alcohol or drug detoxification centres.
Note: However, depending on the insurer, there may be further general and specific exclusions for each cover taken out.
The current age limit for taking out health insurance in Portugal is between 55 and 64 years, which makes it possible for there to be no age limit on remaining insured thereafter.
Health insurance products currently on the market have no age limit for remaining insured, with the premium being updated annually according to the age of the Insured Persons.
For some products, depending on the age at which the product was taken out, there may be an age limit for remaining insured.
This is the period between the date each person is included in the policy and the date the covers come into effect; it is a period during which you cannot make use of your covers.
The waiting period may be general (applying to all covers) or partial (applying to certain covers and/or conditions), so we suggest you check the waiting period applicable to each case in your General, Special and Specific Conditions.
The term 'pre-existing condition' refers to the existence of a pregnancy, condition or symptom prior to the start date of cover under your Policy.
You should contact the provider of the desired specialty directly and book the appointment/medical procedure required.
You can find the provider's contact details on the insurer's website, under “Medical Network”, or by calling the helpline shown on the back of your insurance card. On the day of the appointment, you should identify yourself to the provider using your insurance card.
Home + Condominium Multi-Risk Insurance
This insurance protects the home (building and/or contents) against risks such as fire, natural events, theft and water damage, and can be extended to the common areas of the condominium.
In many plans it also includes liability cover and 24-hour home emergency assistance.
Compulsory insurance covers only the risk of fire to the structure of the property. Multi-risk cover adds water damage, natural events, theft, liability and the contents of the home.
We help you understand which risks are left out of the compulsory minimum in your case.
The sum insured for the building should reflect the rebuilding cost rather than the market value, and the sum insured for contents should reflect their replacement cost. A sum insured that is out of step can lead to proportional reductions in compensation.
We carry out this review with you, because it is the most common error in the policies we analyse.
The condominium insures the common areas and each owner insures their own unit. In practice there are frequent overlaps and gaps between the two policies.
We review both together to ensure there are no uncovered areas or duplicate premiums.
Property
Land Registry Certificate (Caderneta Predial)
Contents
In the case of valuables, electronics or other items of significant individual value, such as jewellery, works of art and the like, we recommend that they be individually recorded with photographs and valued in euros.
For the remaining items, we advise keeping proof of purchase documents showing the date, the price paid and a reference to the type of item.
The deductible is the amount that the Policyholder and/or Insured must bear in the event of a claim; this information should be stated in the Specific Conditions of the policy.
If a claim affects more than one risk covered by the policy, only one deductible will be applied — the highest one among the risks affected.
If a claim results in damage to neighbouring units, the repairs will be covered by the insurer, with only one deductible applied.
In the event of a claim, the Policyholder and/or the Insured must:
Report the claim to the insurer in writing as soon as possible (never exceeding eight days from the day it occurred or came to their knowledge), explaining how it happened, its causes and its consequences;
Take whatever measures are within their power to prevent or limit the consequences of the claim; this may reasonably include preserving any salvage and not altering evidence of the claim without the insurer's authorisation;
Provide the insurer with all information it requests regarding the claim and its consequences;
Not prejudice the insurer's right to recover from the party at fault any compensation it has meanwhile paid to the Insured;
Comply with the safety rules imposed by law, legal regulations or the terms of the contract.
If the Policyholder and/or the Insured fail to comply with these obligations, the cover and the amount of compensation may be affected.
In the event of a claim, the insurer must, promptly and diligently:
Investigate the claim;
Assess the damage;
Pay the compensation due.
The insurer must pay compensation or authorise repair or reconstruction as soon as the investigation and assessment of the damage have been completed. If the insurer has all the information needed to settle the claim and fails to do so within 30 days, it will have to pay interest on the amount of compensation.
The insurer pays compensation in cash if it is impossible or too costly to repair the destroyed or damaged property.
When it is possible to replace, restore, repair or rebuild the property, the Policyholder and/or the Insured must cooperate with the insurer or whoever it appoints.
The proportional rule applies when the sum insured is lower than the cost of reconstruction (in the case of property) or the cost of replacement with new items (in the case of furniture and contents). In this situation, the insurer only pays a part of the loss proportional to the ratio between the cost of reconstruction or replacement at the date of the claim and the sum insured.
For example, if a property whose reconstruction cost is €100,000.00 is insured for €80,000.00, the insurer will only be liable for 80% of the loss, with the remaining 20% borne by the Policyholder and/or the Insured. So, if a claim caused €50,000.00 of damage, the insurer would only pay €40,000.00 (80% of €50,000.00), with the Policyholder and/or the Insured bearing the remaining €10,000.00.
If the opposite is true and the sum insured is higher than the reconstruction or replacement value, the compensation paid by the insurer will be capped at the reconstruction or replacement value.
Where there is no intermediary between the Client and the insurer, the claim should be reported directly; otherwise, it should be reported through the intermediation channels, such as the insurance broker, within eight days of the event occurring or of it coming to the Client's knowledge. In the case of theft/robbery, the incident must also be reported to the relevant police authorities, in order to obtain the police report describing the stolen items, as this document will be needed to process the claim.
To initiate the process with the insurer, the following information should be sent:
Policy number;
Contact person for claim settlement (name, address, telephone number and email);
Date and time of the event;
Detailed description of the claim, identifying the place where it occurred;
Information about the injured party (full name, address, contact details, type of damage — material or bodily), if applicable;
Identification of eyewitnesses and/or authorities that dealt with the incident, if applicable.
Personal Accident Insurance
This type of insurance guarantees payment of the treatment costs required following an accident and, in the event of death or permanent disability, guarantees payment of compensation to the beneficiaries or to the insured person, respectively.
Personal accident insurance covers the person in any circumstance of life, inside and outside working hours. Workers' compensation is compulsory and covers only accidents occurring while at work or commuting.
They are complementary, not alternative, covers, and we explain where one ends and the other begins.
Non-federated sports activity is usually covered. Competitive disciplines and sports considered high-risk almost always need to be expressly mentioned in the policy.
If you practise a specific sport, we check beforehand whether it is included or requires an extension of cover.
Depending on the cover taken out, this may include payment of treatment expenses, a lump sum for permanent disability, a daily allowance for hospitalisation and a lump sum in the event of death.
We size the sums insured with you according to your family and professional situation.
A personal accident is an event that may result in injury or even the death of the Insured Person who suffers an unexpected accident.
It can be a road accident, a burn in the kitchen, a fall on the stairs, or even being the victim of an attack by another person.
The main types of cover under personal accident insurance are:
Death
Permanent disability
Temporary disability due to hospitalisation
Treatment costs for bodily injury
Funeral expenses
Assistance
Participation in federated (organised competitive) sport;
Mountaineering, boxing, surfing, rugby, mountain biking or other sports and activities involving a degree of danger;
Piloting aircraft;
Natural catastrophes, such as earthquakes;
War;
Use of two- or three-wheeled motor vehicles and quad bikes;
Any act or omission by the insured person under the influence of alcohol resulting in a blood alcohol level above 0.5 g/l;
Suicide or attempted suicide;
Bets and dares;
Acts committed by the insured person against themselves;
Acts committed by the beneficiary against the insured person.
This may be possible, provided the insurer is informed in advance so that it can define the scope of its liability.
The Policyholder must report the claim using the insurer's specific claim form.
In addition to the claim report, medical information (a report) and expenses arising from medical care must be submitted.
Life Insurance
Life insurance guarantees a sum to the beneficiaries named in the policy in the event of death or disability of the insured, helping to protect the family financially or settle commitments such as a mortgage.
There are individual and group solutions, adjustable in terms of sum insured, duration and any additional cover required.
Risk life insurance pays out a sum in the event of death or disability during the term of the contract and has no surrender value. Capitalisation products add a savings component to the cover, which can be surrendered.
We clarify which of these two approaches matches the goal you have in mind, because they are different products with different purposes.
Yes. The insurance required by the bank does not have to be taken out with that institution, and can be replaced by another policy with equivalent or better cover.
We review the policy in force and present alternatives with the same cover, indicating what is needed for the transfer.
It depends on the sum insured and your age. Lower sums insured are usually resolved with a health declaration; above certain limits the insurer requests additional tests.
We tell you in advance what each insurer requires, so you know what to expect before going ahead.
Life Insurance;
Marriage/Birth Insurance
Financial Insurance
The insurer must set out in the insurance contract, in a clear and precise manner, which documents are required and the time limits established for this purpose.
Following the recommendation of the Insurance and Pension Funds Supervisory Authority, the documents that insurers may require to pay the surrender value and the redemption value should not exceed the following:
Surrender value
Capitalisation insurance: Citizen Card (or identity card and tax number card)
Capitalisation operations: Citizen Card (or identity card and tax number card) + Capitalisation certificate
Redemption value, in the event of survival
Capitalisation insurance: Citizen Card (or identity card and tax number card) + Birth certificate (if the beneficiary does not appear in person)
Capitalisation operations: Citizen Card (or identity card and tax number card) + Capitalisation certificate
Redemption value, in the event of death
Capitalisation insurance: Citizen Card (or identity card and tax number card) + Documentation relating to the claim report + Death certificate and document proving heir or beneficiary status
Capitalisation operations: Citizen Card (or identity card and tax number card) + Capitalisation certificate + Death certificate and document proving heir status (if the certificate is registered in a specific name).
Additional documents may be required in certain circumstances that justify it (for example, the nature and complexity of the product).
Following the recommendation of the Insurance and Pension Funds Supervisory Authority, payment of surrender and redemption values must be made within the following time limits (counted from the date the insurer receives the necessary documents):
Surrender value: 10 business days
Redemption value, in the event of survival: 5 business days
Redemption value, in the event of death: 20 business days
Longer time limits may be set in certain circumstances that justify it (for example, the nature and complexity of the product).
The following covers may be added to the main covers (Death and Disability): Accidental death and death in a traffic accident; Total or partial disability, occupational disability, or permanent or temporary incapacity.
There are pre-defined sums insured in standard products marketed by insurers, or you may be free to choose the sum insured you wish to take out.
The creation of the Central Registry of life insurance, personal accident insurance and capitalisation operation contracts with a beneficiary (maintained by the Insurance and Pension Funds Supervisory Authority – ASF) aims to make it possible to obtain information about Life Insurance contracts in the event of the death of the insured person or the policyholder.
Insurers are currently required to provide a set of information to the ASF, so that this authority can guarantee any interested party the right to obtain information about the existence of life insurance contracts in which they are named as beneficiary.
The information contained in this registry is available for consultation during the term of the contract and for as long as there are benefits still to be paid by the insurer — in other words, it remains available until the Sum Insured has been claimed.
The Policyholder must report the claim; some insurers have their own specific form for this.
Depending on the cover being claimed under the policy, various documentation will be required, which will subsequently be confirmed by the insurer.
Pet Insurance
It covers veterinary expenses resulting from illness or accident, and may also include liability for damage caused to third parties by the animal and assistance in the event of theft or loss, depending on the plan taken out.
Liability cover is compulsory for dogs considered potentially dangerous, under the applicable legislation. For other animals, taking out cover is voluntary.
We check whether your animal's breed is covered by the legal obligation.
Cover can vary, but generally includes:
Veterinary expenses (consultations, tests, surgeries)
Hospitalisation
Medication
Civil liability (damage caused to third parties)
In some cases, assistance and additional services
Most insurers set a minimum and a maximum age for taking out cover, and some maintain cover beyond that age provided the policy was taken out before it was reached.
We check the limits set by each insurer before going ahead.
As a general rule, pre-existing illnesses or conditions are not covered — that is, health problems already diagnosed before the insurance was taken out.
Yes. Most policies include a waiting period, during which certain covers are not yet active. This period varies depending on the insurer and the type of cover.
The price depends on several factors, such as:
Age and breed of the animal
Covers chosen
Sum insured and deductibles
In general, there are affordable options suited to different needs.
Yes, especially for those seeking cost predictability and access to quality veterinary care, avoiding unexpected expenses in the event of illness or accident.
It depends on the policy. Some policies work with a network of approved providers, while others allow free choice with subsequent reimbursement.
Workers' Compensation
In Portugal, this insurance is compulsory for all employers, covering employees in the event of an accident occurring at the place and during the time of work, including commuting (in itinere).
Self-employed workers can, and should, also take out this cover voluntarily.
As Work Accident Insurance is compulsory, employers are required to transfer liability for compensating damage arising from work accidents to entities legally authorised to provide this insurance.
Self-employed workers — those who carry out an activity on their own account — are required to take out Work Accident Insurance guaranteeing the same benefits as those provided by law for employees.
Besides compensation for temporary incapacity, it covers medical and surgical care, medication, hospitalisation, transport and rehabilitation arising from the accident, as well as pensions in the event of permanent incapacity.
We follow up the process with the insurer from the initial report through to discharge.
A work accident is one that occurs at the place and during the time of work, resulting in bodily injury, functional impairment or illness, and in a reduction in working or earning capacity, or in death.
The following definitions apply:
Place of work — any place where the worker is present, or must go to, by virtue of their work, and where they are, directly or indirectly, subject to the employer's control.
Working time, in addition to the normal working period — the time preceding its start, spent on preparatory or related activities, and the time following it, also spent on related activities, as well as normal or enforced breaks in work.
Teleworking or remote work — the place of work is considered to be that stated in the teleworking agreement.
The amount of earnings to be transferred to the insurer should include the base salary and all other supplementary or additional benefits, whether paid in cash or in kind.
Supplementary benefits are all those that, due to the regularity of their payment, become part of the concept of earnings. Examples include, among others, attendance and productivity bonuses, sales commissions, allowances for flexible working hours, meal allowances, isolation or shift allowances, as well as Christmas and holiday bonuses, which, due to their widespread and compulsory nature, are already part of the said earnings.
Benefits in kind are all those that, although not paid in cash, nonetheless form part of the concept of earnings, provided they are granted on a regular basis.
When the earnings declared for the purposes of the insurance premium are lower than the actual earnings, the insurer is only liable in relation to the declared earnings. In this case, the employer will be liable for the difference regarding temporary incapacity and pensions due, and proportionally for the costs of hospitalisation and medical care.
The insurer must be notified in advance of insured persons travelling abroad in the following situations:
Within the European Union, whenever the stay exceeds 15 days.
To the rest of the world, regardless of the duration of the trip.
Note that, regardless of the length of the trip, in the event of a claim occurring abroad, the insurer will only be liable for treatment, transport and repatriation costs if this is expressly stated in the Specific Conditions of the Policy.
The definition of a work accident also includes those occurring on the outward and return journey to and from the place of work.
Employers, or whoever represents them in the management or supervision of the work, must ensure the immediate and necessary medical assistance to the victim, as well as the most suitable transport for this purpose.
Reporting a work accident is mandatory and must be done electronically within 24 hours of the employer becoming aware of the accident.
As soon as this fact becomes known, the employer must immediately notify the insurer by email, without prejudice to submitting the claim report within the prescribed time limit.
The Work Accidents Act provides for benefits in kind and benefits in cash.
Benefits in kind are benefits of a medical, surgical, pharmaceutical, hospital or other nature, in any form, provided they are necessary and appropriate for restoring the injured person's health.
Benefits in cash are benefits corresponding to compensation, pensions, allowances and subsidies.
As, in these cases, the insurer is only secondarily liable, it is the employer who bears the responsibility of providing all the benefits set out under the right to compensation.
This right does not affect any civil liability for non-material (moral) damages, nor any criminal liability that the employer, or its representative, may have incurred.
Industrial Multi-Risk Insurance
Industrial multi-risk insurance is a solution that protects industrial businesses against various risks, including damage to premises, equipment and goods, and financial losses resulting from unforeseen events.
Only through business interruption cover, which compensates for the loss of income during the period needed to restore activity. It is not included by default in property damage policies.
We size that cover based on your actual operating figures.
They can be insured at replacement value as new or at current value, with very different consequences for the compensation paid. The choice must be stated explicitly in the policy.
We review the inventory and the valuation basis, which rarely keep pace with the equipment stock over the years.
Stock is a separate sum insured within the policy and should reflect actual stock levels, which vary throughout the year.
We help set sums insured that accommodate seasonal peaks without a permanent extra cost.
Cover can vary, but typically includes:
Fire, explosion and natural phenomena
Water damage
Theft or vandalism
Machinery breakdown
Business interruption (loss of profits)
Civil liability associated with the business activity
This insurance is suitable for industries, factories, production units and businesses with industrial activity, regardless of size, that want to protect their assets and operational continuity.
Yes, when this cover is included, the insurance can protect against sudden and unforeseen damage to equipment and machinery essential to production.
Loss of profits refers to the financial losses resulting from the interruption of business activity following a covered claim, such as a fire or serious breakdown.
Yes, most policies include cover for storms, floods, earthquakes and other natural phenomena, depending on the conditions taken out.
The cost of the insurance depends on factors such as:
Type of industrial activity
Value of buildings, equipment and stock
Location and risk exposure
Claims history
Covers and sums insured chosen
Yes. Some common exclusions include:
Natural wear and tear or lack of maintenance
Intentional acts
Certain risks not specifically taken out
It is important to carefully review the terms of the policy.
It can include, as an additional cover, operational civil liability, protecting the business against damage caused to third parties.
The best solution should be defined based on a detailed risk analysis, ensuring that all critical areas of the business are protected.
Property Multi-Risk Insurance
Property multi-risk insurance is a solution that protects buildings, premises, equipment and contents against various risks, providing financial security in the event of a claim.
Buildings, improvements, office and IT equipment, furniture, stock and third-party goods in your care can all be included, each with its own sum insured.
We help draw up that inventory, which is the basis of the whole policy.
Water damage and natural events are standard covers under multi-risk insurance, but with their own excesses and exclusions that vary between insurers.
We compare these conditions in detail, because this is where policies vary the most.
Yes. Even without new acquisitions, rebuilding and replacement costs change, and a sum insured that was adequate a few years ago may now translate into insufficient compensation.
We carry out this review periodically with our clients.
Cover varies, but generally includes:
Fire, explosion and lightning strike
Water damage
Natural phenomena (storms, floods, earthquakes)
Theft or vandalism
Glass breakage
Civil liability associated with the property
It is suitable for businesses, public entities, property owners and asset managers who want to protect their assets against unexpected risks.
No. There are exclusions, such as:
Natural wear and tear or lack of maintenance
Intentional damage
Risks not included in the policy
It is essential to review the contractual terms.
Yes, provided the cover has been taken out; it may include storms, floods and earthquakes, depending on the covers taken out.
Yes, many policies include owner's or operator's civil liability, protecting against damage caused to third parties.
Yes. It can include protection for equipment, furniture, stock and other assets, subject to valuation and definition of the sums insured.
After the event, the claim must be reported to the insurer, which will assess the damage and pay compensation in accordance with the policy terms.
The choice should be based on a detailed analysis of the assets and associated risks, ensuring covers tailored to specific needs.
Credit and Surety Insurance
Credit insurance protects businesses against the risk of non-payment by customers, guaranteeing compensation in the event of non-payment due to insolvency or prolonged late payment.
Surety insurance replaces traditional guarantees (such as bank guarantees), ensuring the fulfilment of contractual obligations towards third parties, such as public tenders, construction works or commercial contracts.
Businesses that sell on credit, exporters, or organisations wishing to protect their cash flow and reduce commercial risk should consider this type of insurance.
Surety insurance is commonly used in:
Public tenders
Construction and works contracts
Supply of goods and services
Performance guarantees and advance payment guarantees
Credit insurance:
Non-payment due to insolvency
Prolonged payment delays
Commercial and, in some cases, political risks
Surety insurance:
Contract performance guarantee
Payment guarantee
Guarantees required in public procurement
Protection against financial losses
Improved commercial risk management
Support in customer analysis
Easier access to financing
An alternative to bank guarantees
Lower impact on credit lines
Greater financial flexibility
Compliance with contractual requirements
Not necessarily. Insurers set credit limits per customer, based on risk analysis and financial history.
Yes. In credit insurance, there are defined default periods before compensation is paid. In surety insurance, the conditions depend on the guaranteed contract.
Yes. There are specific solutions for international markets, including cover for political and commercial risks on exports.
After verifying the default and confirming that the policy conditions have been met, the insurer proceeds with partial or total compensation of the insured amount, as agreed.
Through an insurance broker, such as VCS – Verspieren, who analyses the company's profile and presents a customised solution tailored to the business's needs.
General
An insurance broker is an independent professional who represents the client's interests, not those of any particular insurer. Their role is to analyse each client's needs and present the most suitable insurance solutions, negotiating terms, following up claims and providing ongoing advice throughout the life of the policy.
At Verspieren, we put our experience and market knowledge at the service of individuals and businesses, guaranteeing complete transparency and independence in choosing the best cover.
The process begins with a detailed assessment of the client's needs and risk profile. Based on this analysis, the Verspieren team compares proposals from several partner insurers and recommends the solution with the best balance of cover, service and cost.
Once the policy is in place, we continue to monitor it, helping with claims management and proposing adjustments whenever the client's situation changes.
You can contact us through the Contact page on the website, by phone or by email, listed in Verspieren's general contact details. Our team responds as quickly as possible to any question about policies, claims or new insurance solutions.
Motor Fleet Insurance
There is no magic number, but fleet management starts to pay off once a company can no longer keep track of renewals and claims vehicle by vehicle. The main advantage is administrative: one policy, one renewal, one point of contact.
Our team analyses the make-up of your fleet and advises whether moving to a single policy is worthwhile in your case.
Vehicles are added and removed by notifying the insurer, taking effect on the agreed date, with no need to redraft the contract. The premium is then adjusted according to the changes made during the period.
We monitor these changes for you, so that no vehicle is ever on the road without cover, and no premium is paid for vehicles that have already been disposed of.
Yes. Passenger cars, commercial vehicles, heavy goods vehicles and industrial machinery can all sit on the same policy, although with different conditions and premiums depending on how each one is used.
We help structure the fleet by type of use, which is what matters most in the risk assessment.
The claim is reported and settled under the fleet policy, without the driver having to handle the process individually. The fleet's claims history is then taken into account at the next renewal.
We follow up the process with the insurer and keep the company informed until it is closed.
Group Health Insurance
The company's employees, and in many plans also their spouses and children, subject to the conditions agreed in the policy. Membership can be compulsory or optional depending on how the plan is designed.
Our team helps define the group of people to be covered, which is the decision with the greatest impact on the premium.
In group plans with a sufficient number of members, the individual questionnaire is often waived, one of the main advantages compared with individual cover. Below that threshold the insurer may require it.
We check with each insurer the waiver conditions that apply to the size of your company.
Cover ends when the employee leaves, on the date set out in the policy conditions. Some contracts allow continuation on an individual basis, preserving seniority and waiving new waiting periods.
We check whether this continuation exists in the plan under consideration, because not all plans provide for it.
As a rule, yes, because the risk is spread across a larger number of people and administrative costs are lower. The difference depends mainly on the size and age structure of the group.
We prepare a comparison with real figures for your specific case before any decision is made.
Group Life Insurance
It guarantees a sum to employees' beneficiaries in the event of death or disability, acting both as a social benefit and, in many cases, as a way of meeting obligations set out in collective regulation instruments.
Our team checks which obligations apply to your sector before designing the plan.
It can be a flat sum insured or one linked to each employee's pay, for example a multiple of their annual salary. Both structures are common.
We help choose the structure, which has a direct impact on the premium and on how the benefit is perceived.
No. The contract is taken out with the company, and the people covered are updated periodically by reporting changes, with no need for a new contract.
We take care of this update for you, making sure no employee is left uncovered.
From a certain number of members onwards, it is common to have a sum insured accepted with no medical formalities, with the questionnaire applying only above that limit.
We check with insurers the limit that applies to the size of your company.
Already part of our network?
Log in to our client area or access the exclusive agent portal.

Differentiating insurance solutions
Receive a proposal tailored to your profile and needs
Contact us